How Licensing Affects Game Providers, Not Just Casinos
When a casino gets licensed, only part of the regulatory burden falls on the casino operator. The game provider bears most of the real compliance cost.
The licensing narrative in gambling journalism has a blind spot. When a major regulatory body like the UK Gambling Commission (UKGC) or Malta Gaming Authority (MGA) approves a casino, the headlines focus on the casino operator. "DraftKings receives UK license." "FanDuel approved by New Jersey." But the actual regulatory mechanism is more distributed than that. Game providers (the companies that make the slots, table games, and sports betting systems) face equally stringent requirements, sometimes more stringent.
Consider how this actually works. A casino operator like Stake.com cannot simply install any game it wants. Every single game must be independently licensed by the jurisdiction where it operates. Pragmatic Play (provider of games for Stake) must apply for and receive licensing approval in each territory. That's not a one-time process. Pragmatic Play must maintain active compliance with UKGC standards, Curaçao eGaming standards, and various other regulatory frameworks simultaneously. This costs money.
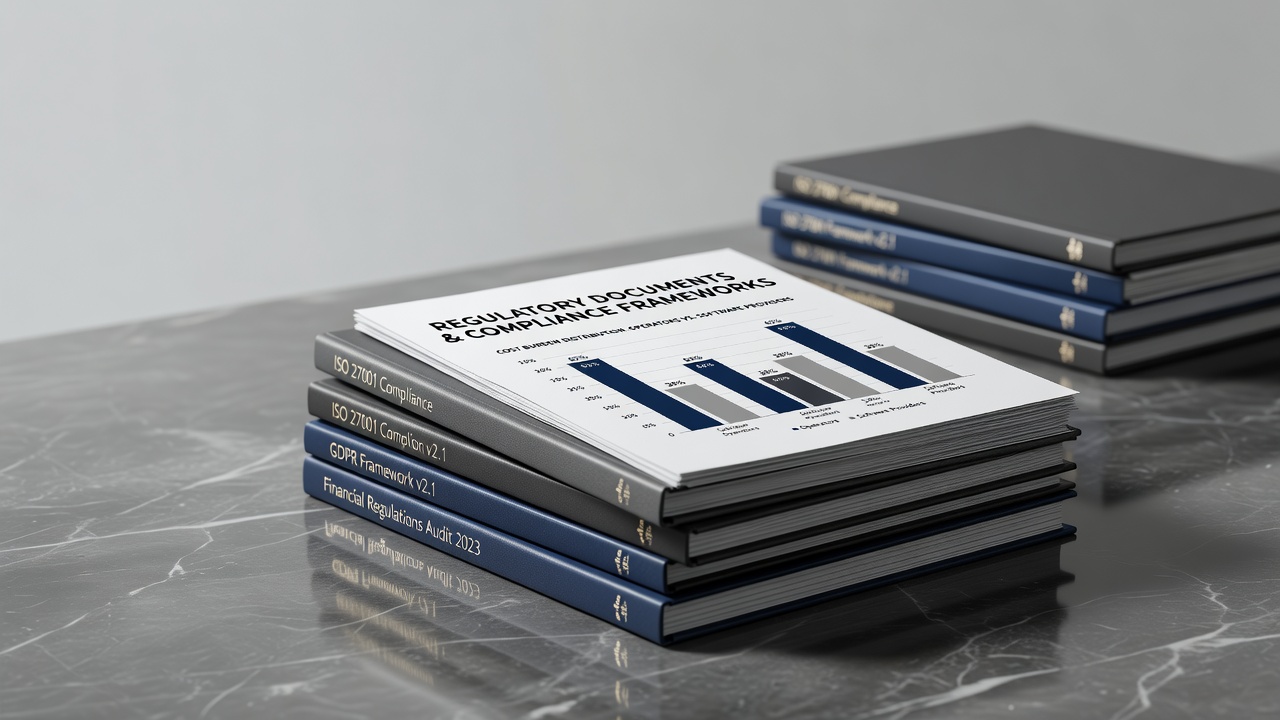
The licensing cost structure looks like this for a mid-size provider: compliance officer salaries (roughly 150,000 to 200,000 GBP annually per jurisdiction), legal consultation (50,000 to 100,000 GBP per year), technical audits to verify RNG (Random Number Generator) integrity (25,000 to 75,000 per year), and ongoing testing and certification (another 30,000 to 50,000 per year). A provider operating in four major jurisdictions faces roughly 600,000 to 1.2 million GBP annually in pure compliance overhead.
This creates a barrier to entry. A solo developer cannot afford this. A provider must reach scale (perhaps 50 million dollars in annual gaming revenue) before the compliance cost becomes mathematically manageable. This naturally concentrates the market. Pragmatic Play, Playtech, NetEnt, and Microgaming dominate because they can amortize that compliance expense across hundreds of casino operators. A startup cannot.
The RTP lockdown
Here's where provider licensing gets interesting. The UKGC specifies that slots must pay out at a minimum RTP (Return to Player) of 92 percent for standard games, 88 percent for progressive jackpots. That's the legal minimum. But once Pragmatic Play files its RTP math with the UKGC, that rate becomes locked. The provider cannot adjust the RTP without resubmitting for approval. This takes 6 to 8 weeks.
Meanwhile, a casino operator using Pragmatic Play games can set different RTPs (within a range). A UK operator might offer 95 percent RTP to competitive pressure. A less competitive market might drop to 92 percent. The provider's code supports this flexibility. But every RTP configuration must be pre-approved by the regulator. The provider essentially submits a mathematical range ("games will be configured between 92 and 97 percent RTP") and the UKGC approves that range. The casino picks where within that range to operate.
Providers who miss this submission deadline face hard business consequences. A game cannot launch until the regulator approves the RTP math. If Pragmatic Play miscalculates or submits incomplete documentation, the launch delays. This has happened. In 2018, a NetEnt game launch in the UK delayed six weeks due to incomplete RNG documentation.
The business consequence: consolidation
Smaller providers fold. BGaming, an up-and-coming provider, spent millions pursuing licensing in multiple jurisdictions, then pivoted heavily toward crypto-gambling jurisdictions (Curaçao, Alderney) where compliance is lighter. The regulatory cost in major markets exceeded the revenue they could generate. For a company with 40 million in annual revenue, adding 1.2 million in compliance costs is tolerable. For a company with 15 million in revenue, it's crushing.
This regulatory structure actually benefits large casinos, not small ones. You might think the opposite. Actually the opposite is true. A large casino can absorb slightly higher game costs because it has negotiating power with providers ("we'll take 500 of your games instead of 50, so discount us on licensing fees"). A small online casino cannot. They pay retail prices for provider content and retail-price compliance. This means the regulatory framework, designed to protect players, inadvertently advantages already-large operators.
The MGA (Malta Gaming Authority) has simplified this slightly. They allow providers to submit unified documentation for multiple jurisdictions, reducing duplicate submissions. UKGC has not done this. Each jurisdiction requires separate licensing. This is why Pragmatic Play maintains separate legal offices in London, Madrid, and Stockholm. The compliance work cannot be centralized.
What this means for players
Game diversity matters for player experience. More providers means more game variety, better innovation, more competition on payout rates. Licensing consolidation reduces diversity. A market with three major providers offers less innovative game design than a market with ten.
But here's the irony: player protection improved as licensing costs rose. The jurisdictions that impose the highest compliance costs (UKGC, UK-certified offshore operators) have the lowest problem-gambling rates in Europe. Licensing costs correlate with protection. The regulatory burden that narrows provider markets also tightens controls on game mathematics, player data, and responsible gambling features.
For players, the outcome is paradoxical. You have fewer game options. But the games you do have are more heavily audited, the math is more transparent, and the operator is more accountable. The licensing mechanism works. It's just expensive.
Markets in this line
Keep reading